Key Takeaways
- There is no universal five-figure phone policy: eligibility, covered events and payout depend on the exact contract, state and handset.
- Compare the documented cost to replace your edition with the per-claim limit, deductible and any depreciation or substitution rule.
- A manufacturer warranty, accidental-damage service plan and theft or loss insurance are different promises.
- Get written answers on bespoke finishes, international incidents, repair networks and required claim evidence before buying coverage.
Phone insurance for a five-figure handset is useful only if the policy covers the exact device, the loss you fear and enough of the replacement cost to matter. A plan that accepts 鈥渟martphones鈥?may still have a per-claim limit below the price of a premium or customised edition, or may replace it with a different model. The answer comes from the applicable certificate and written insurer confirmation, not from a product badge or a general sales page. Use this contract-reading checklist to find the gap before an incident.
Separate warranty, service plan and insurance
A manufacturer warranty commonly addresses defects under its stated conditions. A device service plan may add specified accidental-damage repairs. Theft or loss protection may be a separate insurance feature or a different policy. These arrangements can have different providers, deductibles, claim limits and procedures. Never assume that a warranty covers a dropped phone simply because the manufacturer also offers repairs.
VERTU's current repair policy sets out its own coverage and exclusions. Check the version, market and documents that apply to your order. A warranty response to a manufacturing issue is not evidence that accidental damage or theft is insured. Likewise, an insurer's promise to pay does not guarantee immediate access to authorised repair parts or a like-for-like replacement.
The US National Association of Insurance Commissioners explains how insurance and deductibles work. The principle is simple: read the policy's covered events, exclusions, limits and your share of the loss. The details for a luxury handset are specific to the contract.
Run the replacement-cost calculation
Start with a current written quote for the exact handset configuration you would need to replace: model, finish, storage, special materials and any documented custom work. Then obtain the proposed policy's per-claim maximum, total term or annual limit, deductible and valuation method. Ask whether taxes, shipping, accessories or bespoke work are included. 鈥淔ull coverage鈥?is not a useful number until those terms are known.
For an illustrative calculation only, suppose an edition would cost $20,000 to replace, the policy has a $5,000 per-claim cap and a $500 deductible. Even if the event is covered, the owner could face a substantial gap. The arithmetic depends on the contract's order of calculation and valuation method; do not use this example as a quote. Ask the insurer to show the expected payout for your exact edition in writing.
Check whether the insurer pays replacement cost, actual cash value or a repair cost, and whether it can provide a new, refurbished or 鈥渓ike kind鈥?device. A payment based on a standard handset may not recreate a limited finish. Asurion's general mobile-insurance FAQ says some carrier programmes may supply a new or refurbished replacement and that colour, model or features may differ. That is an example of a clause to investigate, not a statement that every Asurion programme or VERTU device has the same terms.
Check which incident is actually covered
Ask the provider to distinguish accidental physical damage, mechanical breakdown, theft, accidental loss and unexplained disappearance. A policy may cover one and exclude another. Cosmetic scratches, wear, liquid damage, unattended property, intentional damage or unauthorised repair can also be treated differently. The definition of 鈥渢heft鈥?may require evidence that a simple loss does not.
State Farm describes a personal articles policy as potentially offering broader protection and higher limits for eligible valuables, with exclusions and item-specific eligibility. Its page lists examples of electronics but does not establish that a given luxury smartphone is eligible. Ask an agent whether your precise handset can be scheduled or otherwise insured, at what stated value and under which policy language.
Do not rely on a homeowners, renters, credit-card or carrier benefit without checking its device eligibility, sublimit and exclusions. These programmes can interact, but having several labels does not mean you can recover more than the contract allows. Ask each provider how other coverage affects a claim.
Ask the repair and replacement questions that matter
A high-value handset can be difficult to replace quickly if its materials or edition differ from a mass-market phone. Ask whether the provider uses the manufacturer's authorised service channel, who chooses the repairer, whether original parts and finish can be restored, and what happens if the model is unavailable. Find out whether a cash settlement is possible and how it is valued. A 鈥渞eplacement phone鈥?clause may mean an equivalent functional device rather than the exact design you purchased.
If you travel, ask where coverage applies, whether you can report an incident abroad, which currency a deductible uses, who pays shipping and customs charges, and how long a repair or settlement may take. Do not assume that 鈥渨orldwide coverage鈥?means local repair or same-day replacement everywhere. Read the territorial provision and service procedure separately.
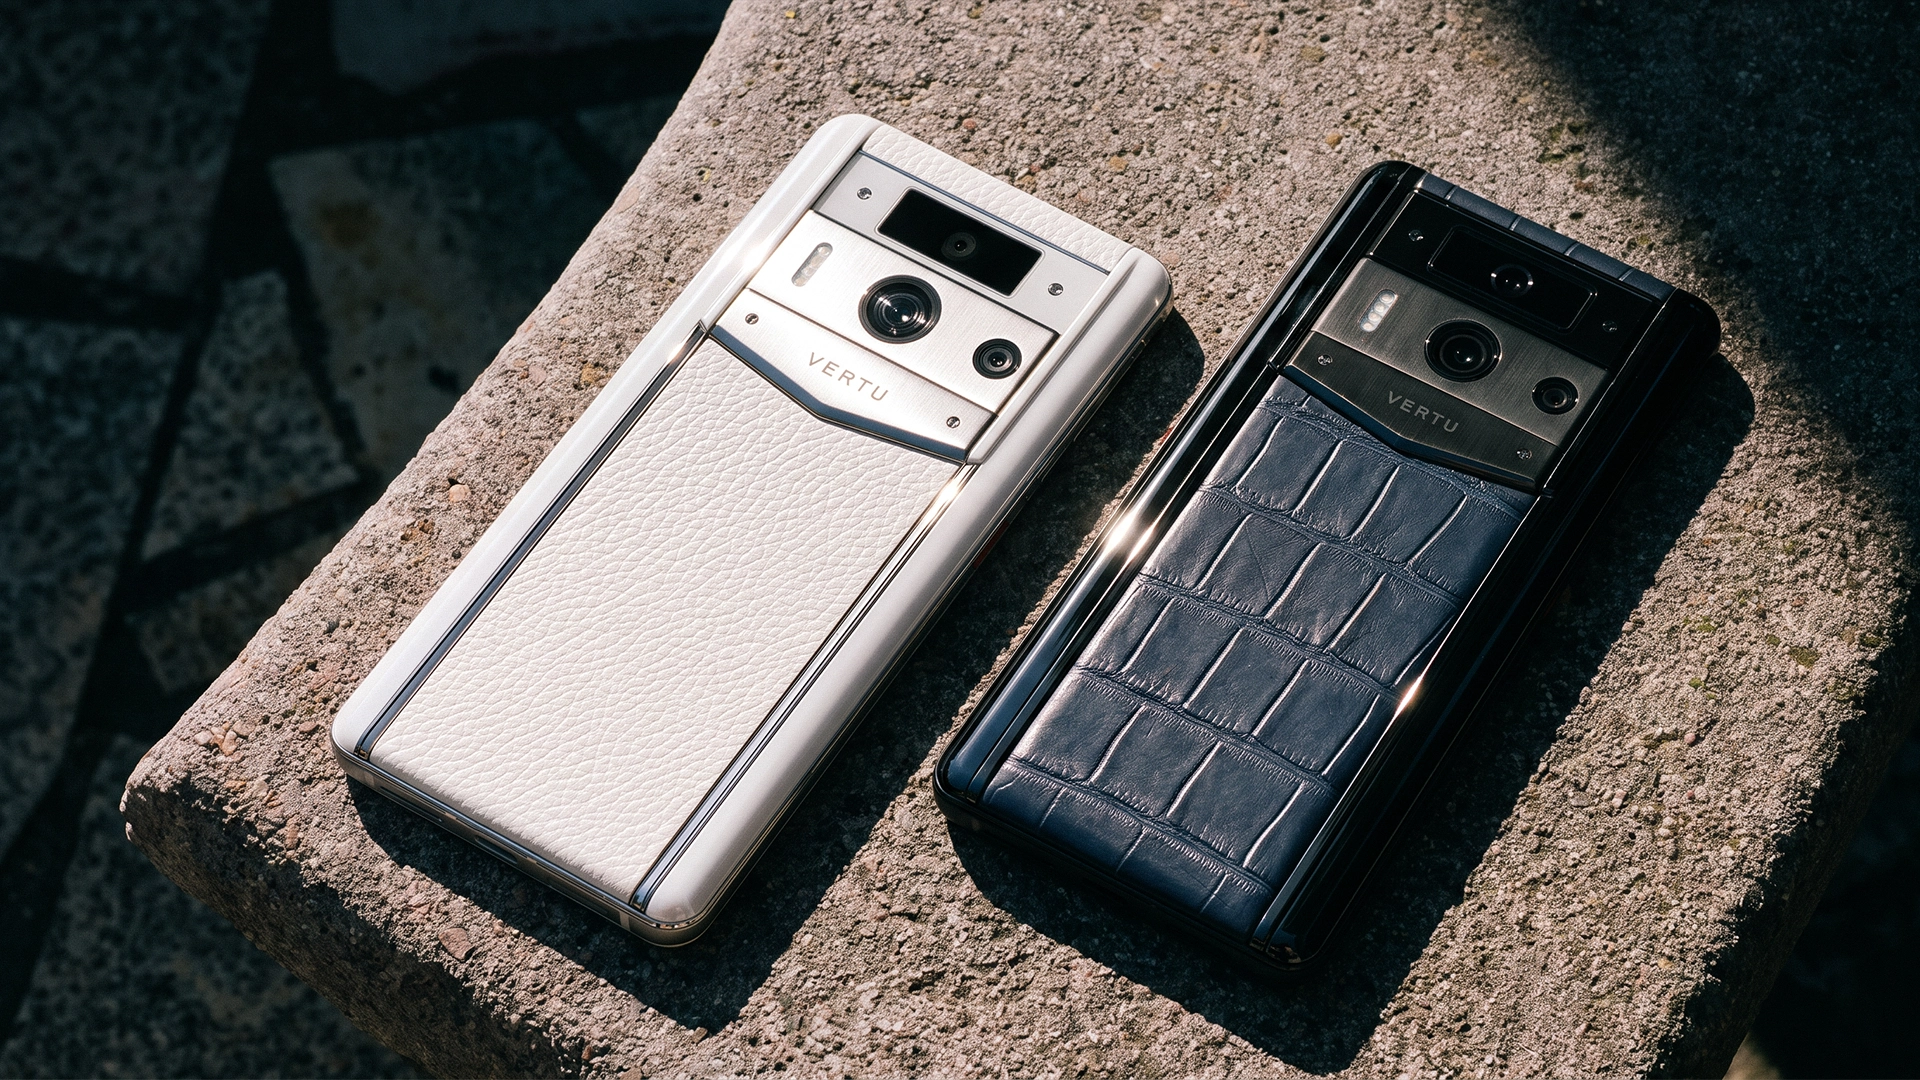
The METAVERTU MAX collection illustrates why edition-level verification matters: the current official catalogue contains different materials and finishes, including premium options. This article does not assert that any insurer will cover a particular VERTU edition. Confirm the exact SKU and current replacement quotation with VERTU before asking for insurance terms.
Build a claim-ready ownership record
Keep the original invoice, proof of payment, exact model or SKU, serial number or IMEI, and photographs that show the handset's finish and condition. Retain customisation documents and a current replacement quote if the item is unusual. Save the policy certificate, declarations, endorsements and any written exchange with the insurer confirming eligibility and stated value. Store copies somewhere you can reach without the phone itself.
After a loss, follow the contract's notification deadline. Ask whether a police report, carrier suspension record, location-service status, repair estimate or damaged device must be supplied. Do not assume that one plan's deadline applies to another. Preserve the device and packaging if a repair claim requires inspection, unless safety instructions say otherwise. For theft, protect accounts and SIM access promptly through your carrier and account providers.
Data protection is a separate issue. Insurance may help pay for hardware, but it does not reconstruct contacts, authentication keys or private files by itself. Keep backups and recovery methods consistent with your security needs. VERTU's phone price guide gives broader context for why configurations vary; use actual purchase and replacement documents for any insurance application.
Questions to send an insurer before you pay
- Is this exact model, edition, finish and serial-numbered handset eligible for the proposed plan?
- What is the maximum payable for one incident and over the policy term, after the deductible?
- Which events are covered: accidental damage, liquid damage, theft, loss and mechanical breakdown?
- Is the settlement based on repair cost, replacement cost or depreciated value?
- May the provider substitute a refurbished, different-colour or different-model device?
- Are customised materials, engraving, taxes, shipping and accessories included in the insured value?
- What happens if damage or theft occurs outside the United States, and where would repair take place?
Ask for the answer in the policy, endorsement or a written confirmation that identifies your actual device. If the provider cannot confirm eligibility or valuation, do not treat a generic online quote as complete protection. This is a decision framework, not an endorsement of any specific insurer or legal interpretation of a policy.
FAQ
Does ordinary phone insurance cover the full price of a five-figure handset?
Only if the policy accepts the exact device and its valuation and limits are high enough. Compare the written claim cap and deductible with a current replacement quote.
Will an insurer replace the same edition and finish?
Not necessarily. Some plans permit a different or refurbished replacement. Read the like-kind and settlement wording, and ask how a bespoke finish is valued.
Is theft covered when I travel abroad?
That depends on the theft definition, territory, notice rules and documentation in your contract. Confirm both coverage and the practical claims route before departure.
Does a VERTU warranty cover accidental damage?
Do not assume it does. Read the current repair policy and the terms applicable to your order; a warranty and accidental-damage insurance have different purposes.
What evidence should I keep for a claim?
Keep purchase proof, the exact device identity, configuration photographs, customisation records, the policy and written insurer confirmations. Follow the applicable claim's evidence requirements after an incident.
Conclusion
For a five-figure handset, insurance is a contract and a calculation. Verify that the exact edition is eligible, compare its documented replacement cost with the payout limit and deductible, and understand what happens after damage, theft or loss at home or abroad. Keep the evidence that would let you make a claim, and obtain the insurer's answer in writing before relying on the plan.